
Starting again
Buying Property After Separation or Divorce
Buying property after separation starts with what is actually possible now, not with what was lost. This page is for anyone weighing up a home or an investment after a relationship has ended, often on one income and often with children whose lives have already been turned upside down. I'm Aimee Templeman, and I help you sort the decision into an order you can manage, over a set number of sessions.
It is a specialised part of my property decision coaching practice, shaped by my own hard seasons as much as by my licences.
Where to begin
Buying again after separation
Buying again after separation is possible for more people than expect it, but rarely in the shape they first picture. Coaching starts with your settlement figures, your income and your children's needs, then tests the options honestly before you commit to any of them.
Most people arrive carrying two questions at once. The practical one: can I afford to buy, where, and when? And the heavier one underneath: will I ever feel settled again? The second question tends to rush the first. People sign on something within months because owning a place feels like proof that life is back on track.
That instinct is understandable, and it is where expensive mistakes happen. A purchase made to calm the panic of this month is often one you are still paying for in five years. So we slow it down. Not forever, just long enough to see the whole board.
Practically, that means knowing the final settlement position before spending any of it, and understanding what your borrowing looks like on your own income. Your family lawyer and broker answer those. My part is to help you ask them the right things, then make sense of the answers together.
I also bring something less tidy. I have been through difficult relationships and the slow rebuild afterwards. I know how loud the pressure to "just get it sorted" can be, and how much quieter decisions become once someone else is helping you hold the plan.
Who this is for
- Separated or divorced, and wondering whether buying again is realistic
- Holding settlement money and unsure what to do with it
- A single parent trying to stay close to school and friends
- Off the title of the old home and starting from a smaller deposit
- Making a major money decision alone for the first time in years
Legal and finance questions after separation are referred to a family lawyer, solicitor and broker. Coaching sits alongside them.
Options, not verdicts
What is actually possible now
Separation usually resets your asset position. It does not reset your capacity: your income history, your judgement and what you learned the first time. What is possible now comes from an honest look at both, which usually reveals more than one route forward.
Route one
Buy a home near the children
Right when the numbers allow it on one income without draining every buffer. Often means a smaller place, or a townhouse instead of a house, in the same school area.
Route two
Rent locally, invest elsewhere
Keeps the children's routine intact while part of the settlement goes into a property where prices and rents suit your budget. You own something without forcing a move.
Route three
Rebuild first, buy later
Sometimes the strongest decision is to wait a year: let the settlement finalise, build a buffer and see what your new budget really looks like before borrowing.
There is help for some people in this position. As at October 2026, the Australian Government 5% Deposit Scheme includes single parents and legal guardians, with a minimum deposit of 2 per cent and no lenders mortgage insurance. Eligibility and price caps apply, and a participating lender confirms whether you qualify.
Before you spend any settlement money, ask your lawyer whether the settlement is final. Money and assets acquired after separation can still come into the picture, and time limits can apply to property applications.
If you were never on the title of the old home, your starting deposit may be smaller, but your credit file and income are your own. That is a real foundation, even when it does not feel like one.
Moneysmart's separation financial checklist is a sensible companion while you gather the paperwork. And for buyers going it alone by choice or by circumstance, buying alone is not a backup plan explains why one income can still build something solid.
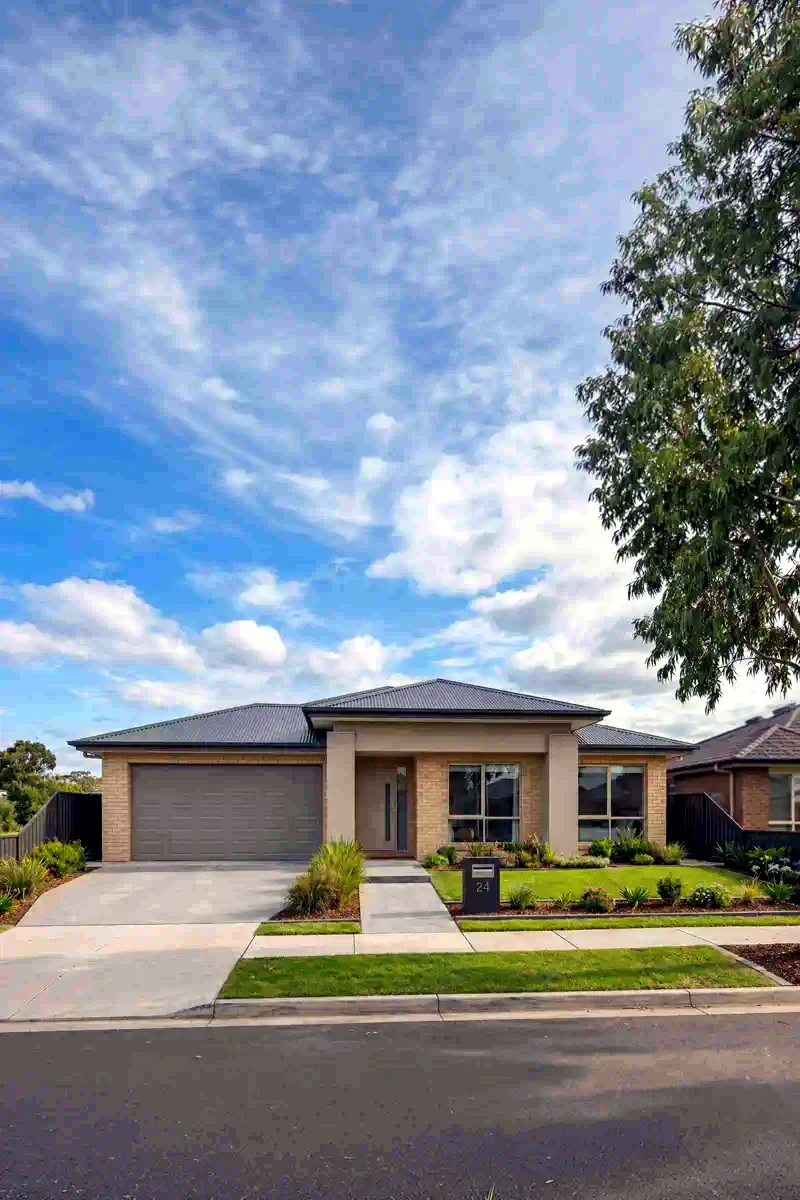
The Newcastle region home bought by the Kellyville client: $820,000, four bedrooms, two bathrooms, renting at $720 a week. Individual circumstances and results vary. General information only, not financial advice.
Kellyville, NSW
Stability for the kids comes first
For parents, the children's stability is the first test every option must pass. Schools, friends, routines and the other parent's home all shape where you can live. Once that is protected, the property question gets much easier to answer.
One of my clients, 38 and recently separated, made her line clear in our first session: she would not disrupt her children's lives again. She stayed in Kellyville, near school and friends. But on one income, buying locally was out of reach, renting long-term felt like going backwards, and she did not want to buy something just to own a place again.
She thought she had to choose between staying put and moving forward. That belief was the real blocker. We separated where she lived from what she owned. She kept renting in Kellyville, put part of her $1.5 million settlement, not all of it, into an investment in the Newcastle region, and kept the lending conservative around her new position.
She kept her children's stability and bought again, and she kept a large share of her settlement in reserve. Her words, from her testimonial:
"After my separation, I genuinely didn't think buying again was an option. I wanted to stay in Kellyville for my kids; their worlds were already spinning, and I only cared about keeping things stable. What shifted for me was realising I didn't have to choose between their stability and moving forward."
More clients describe their own decisions on the client testimonials page.
The method, applied
The five phases after separation
The five phases give a chaotic season an order. Clarity before Direction, Direction before Decision, and support continuing well after settlement. Each phase answers one question, so you are never trying to solve everything at once.
| Phase | The question after a separation | What you have at the end of it |
|---|---|---|
| Clarity | What do I actually have, earn and owe now, on my own? | Your position on paper: settlement figures, income, debts and a monthly budget |
| Direction | What do I want, as opposed to what I feel I should do to look recovered? | Your priorities in order, children first if you have them, and a budget ceiling |
| Decision | Which route: buy a home, rent and invest, or wait? | A choice you can explain, made without waiting for perfect certainty |
| Stability | Is the new arrangement holding up week to week? | Cash flow checked against the plan and a review in the first months |
| Continuum | What did this teach me, and what comes next? | A sense of progress and, when you are ready, the next decision |
The phases are the same ones I use for life and career decisions, which is useful here, because separation rarely stays in one lane. You can read how each one works on the page about the five-phase Continuum Pathway framework.
Beyond the purchase
Rebuilding the rest of your life
A property decision is often the first big choice made alone after a separation. Making it well tends to rebuild confidence in everything else. If the harder work is trust in yourself, routine or direction, coaching can cover that too.
Clients often tell me the purchase was not the hardest part. The hardest part was trusting their own judgement again after years of deciding with someone else, or deferring to them. A clear process helps with that, because each small decision made well becomes evidence you can rely on.
Some clients also want to understand money properly for the first time, because a former partner always handled it. That is a skill, not a personality trait, and it can be learned at any age, which is what money and independence coaching is for. Being the one who reads the loan documents and signs them is part of the rebuild too.
For the wider work, from confidence and routine to working out who you are now, see coaching for rebuilding after separation, burnout or big change.
Coaching is not therapy
Separation can bring grief, anger and exhaustion. Coaching supports decisions and action; it does not treat distress. If you are struggling to cope, a GP, psychologist or counsellor is the right first step, and coaching can sit alongside that support when you are ready.
Can I buy on one income after separation?
Often, yes, though the budget may be smaller than before. Lenders assess your own income, expenses and deposit. A broker will tell you your borrowing range, and coaching helps you decide how much of it to use, which property type fits, and whether buying now or later protects you and your children best.
Do you help with the financial settlement?
No. Settlement is legal work for your family lawyer, and I do not negotiate it or advise on what you are entitled to. Where I help is before and after: understanding what different settlement outcomes would mean for your housing options, and planning how to use the money once the settlement is final.
Do you work with single parents?
Yes, often. Many of the people I coach after separation are single parents, and the children's stability shapes every option we look at, from school zones to bedroom numbers. Sessions are by video, so they can fit around school runs and custody arrangements, or in person in Norwest by arrangement.
Asked gently, answered plainly
Questions after a separation
Three questions people bring to a first call. If yours is more personal than these, bring it anyway.
One conversation
Book a quick chat
You do not need a plan before we talk. Our first conversation is free: a quick chat over video. It lasts about fifteen minutes. Share whatever feels right about what has happened and what you hope comes next. We will work out together whether coaching would help right now.
Some people book while the settlement is still being negotiated, so they understand their options early. Others come a year or two later, ready to buy. Both timings work. If it turns out you need a lawyer or a counsellor more than a coach at this stage, I will tell you, and point you toward the right kind of help.
Property is one part of what I do. The main coaching page covers life and career decisions too.
What coaching involves
- Four one-on-one sessions over eight weeks, in person or online
- $1,000 per program, workbook and exercises included
- All four sessions completed within 10 weeks of starting
- Text or voice memos between sessions
- Returning clients: $750 for another program within 12 months
- Free rescheduling with 48 hours' notice, plus one late change per program
The Continuum Pathway provides coaching. It isn't counselling, psychology or a crisis service. If you need urgent support, call 000 or Lifeline on 13 11 14. General information only. It is not personal financial, legal or tax advice. Speak to a licensed professional about your circumstances.